 Forbidden Finance
Open Enrollment Decoded: HSA vs. PPO vs. EPO vs. HMO at Your Salary Level
Open enrollment math by salary: compare HSA vs PPO vs EPO vs HMO costs for $75K and $150K earners, with tax savings, deductibles, and out-of-pocket maxes.
Tag
Posts tagged “Financial Planning”.
Open enrollment math by salary: compare HSA vs PPO vs EPO vs HMO costs for $75K and $150K earners, with tax savings, deductibles, and out-of-pocket maxes.
October money checklist: prep open enrollment, check FSA balances, top up holiday cash, book the CPA, plan giving, and set holiday budgets early.
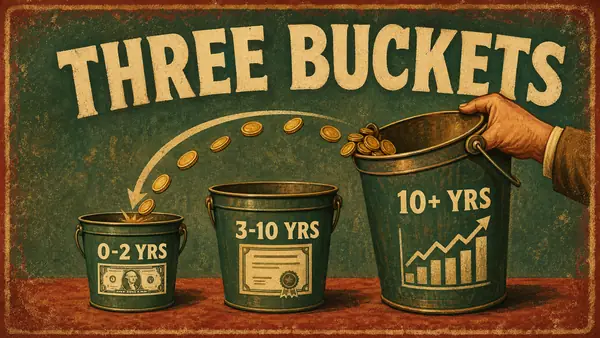
Retirement bucket strategy for the decade before retirement: split cash, bonds, and stocks to reduce sequence risk and make withdrawals calmer across accounts.
Multigenerational household finance shows how shared housing, caregiving, and documented family loans can lower costs without rigid rules.
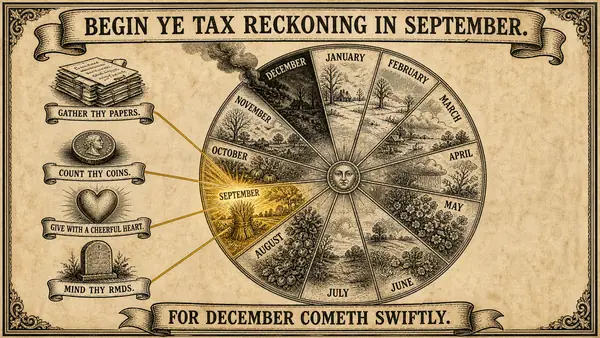
Year end tax planning starts in September: harvest losses, model Roth conversions, bunch deductions, plan RMDs, and true up payments before December panic.
Estate paperwork most families skip, from wills to beneficiary forms, with clear costs and where to start before loved ones are left guessing.
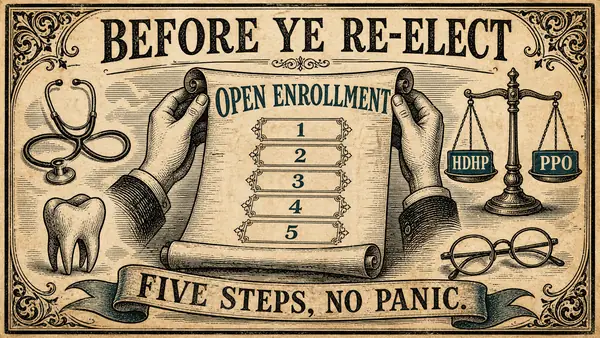
Open enrollment prep gets easier with a five-step worksheet to compare health plans, FSA/HSA choices, and voluntary benefits before renewal.
401(k) loans and hardship withdrawals look easy. Learn the 2026 IRS rules, compounding cost, and rare exceptions before tapping retirement savings.
A fall financial reset plan: clean up accounts, refill savings, pre-game taxes, and lock holiday spending before Q4 turns January into catch-up.
Labor Day weekend money moves you can finish in 30 minutes, from HSA and IRA checks to credit freezes, FSA balances, and October sinking funds.
Dual-currency living tips for expats and cross-border workers: cut transfer friction, plan FX moves, track taxes, and budget cleanly across currencies.
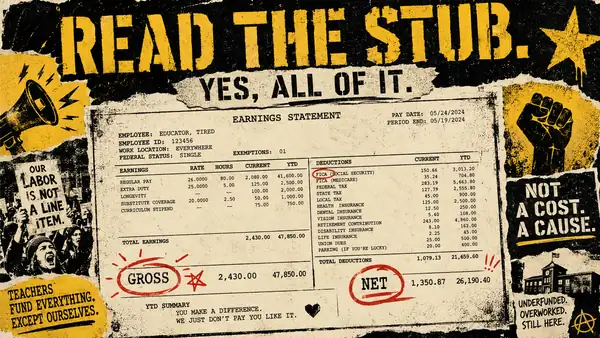
Your pay stub is not a mystery novel. It is a receipt for your labor, and one careful read can show where your money is actually going.
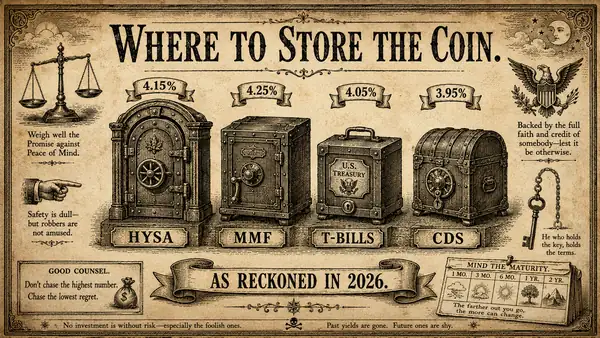
Your cash deserves better than a sad big-bank savings rate. Here is how to match HYSA, money market, T-bills, and CDs to the job.
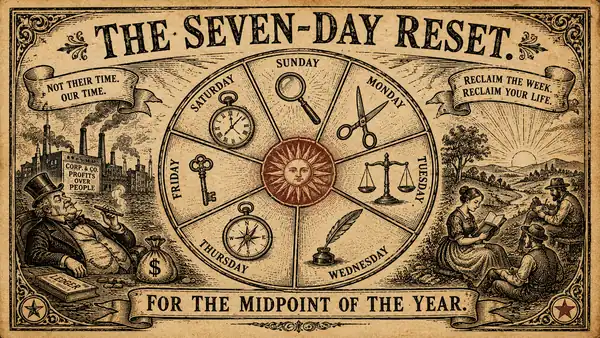
Seven days. Thirty minutes each. A midyear money reset for people who like their finances honest, useful, and only mildly annoying.
Juneteenth is not a branding moment. It is a reminder that systems shape wealth, and that the tools available now are still worth using with care.
The 3-6 month rule is useful, but incomplete. Your real emergency fund target depends on income stability, housing risk, and how many “surprises” are actually just bills wearing fake mustaches.
Another tie says, "I panicked at 4 p.m." This one helps Dad find old accounts, clean up beneficiaries, and make his money less weird.
The usual retirement benchmarks make people feel terrible. Here is the less-annoying version: what counts, what does not, and how to move the next dollar.
Month nine is where debt payoff stops feeling heroic and starts feeling beige. Here is how to keep going without turning your life into a punishment schedule.
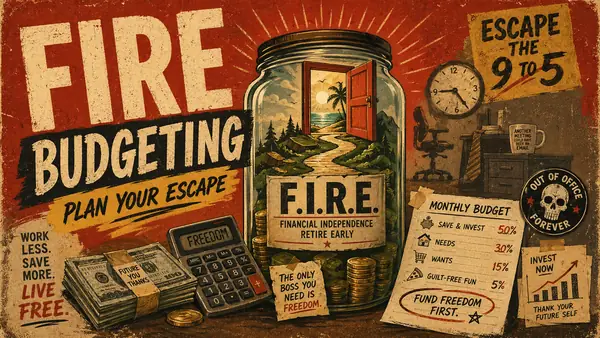
FIRE budgeting helps you turn spending, saving, and investing into a clear path toward financial independence. Here’s how the math works, without spreadsheet gymnastics.
Not all budgeting methods are created equal, and some are objectively more annoying than others. Here’s how 8 popular budgeting systems actually work — and which one might fit your life.
Start free. No credit card, no ads, and no selling your data to make up the difference.