 Forbidden Finance
Why It’s Called 403 Finance: The Meaning Behind Forbidden Finance
403 Finance comes from 403 Forbidden. The name reflects exactly what we wanted this app to reject: budgeting shame, rigid money rules, and creepy data-selling nonsense.
403 Finance, Inc.
We build two products with one rule: your financial data is not for sale. Forbidden Finance is a budgeting app for households. Transmute is a message-conversion API for banks. Neither one funds itself with your data.
Why we exist ↓For people & households
Eight budgeting methods, automatic bank sync, and your net worth in one view. Your data is isolated and encrypted at the database layer, and the subscription is the entire business model.
Explore Forbidden Finance
For banks & fintech developers
A stateless API that converts SWIFT MT messages to and from ISO 20022. Message bodies are never persisted and never logged.
Explore TransmuteWhy we exist
Financial software has quietly settled on a business model where you are the product. We took the opposite bet: software funded by the people who use it. Forbidden Finance never sells or shares your transactions. Transmute never even stores the messages it converts. Different products, same principle: your financial data returns 403 to everyone but you.
We make money one way: you pay for software you find useful. With no advertisers and no data buyers in the room, we never have to choose between revenue and your privacy.
Forbidden Finance isolates and encrypts your data at the database layer. Transmute goes further and simply never stores what it converts. Privacy is the default architecture, not a premium add-on.
We build on proven technology and publish every price. The exciting part should be your money, not our software.
Practical guides from the people building the software.
403 Finance comes from 403 Forbidden. The name reflects exactly what we wanted this app to reject: budgeting shame, rigid money rules, and creepy data-selling nonsense.
Most budgeting apps make money feel like detention. We built Forbidden Finance to make personal finance more flexible, more private, and a lot less miserable.
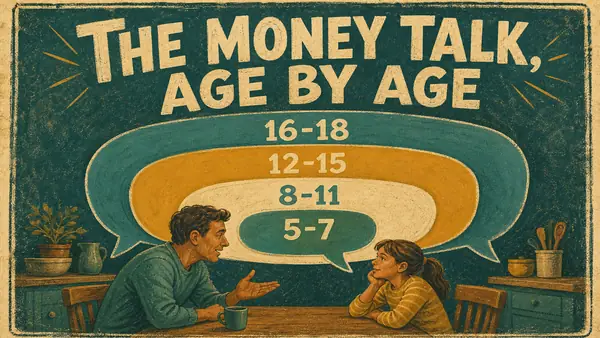
How to talk to kids about money at every age, with real parent scripts for needs vs. wants, saving, budgets, debt, cars, college, and a first credit card.
FSA vs HSA, decided fast: 2027 limits, rollover rules, eligibility, and the October open-enrollment choice that can swing about $5,000 in tax-advantaged room.
Open enrollment math by salary: compare HSA vs PPO vs EPO vs HMO costs for $75K and $150K earners, with tax savings, deductibles, and out-of-pocket maxes.
Halloween spending has doubled since 2010. Keep the fun and cut the cost with costume swaps, decor rotations, potlucks, and a $50 family challenge.
October money checklist: prep open enrollment, check FSA balances, top up holiday cash, book the CPA, plan giving, and set holiday budgets early.
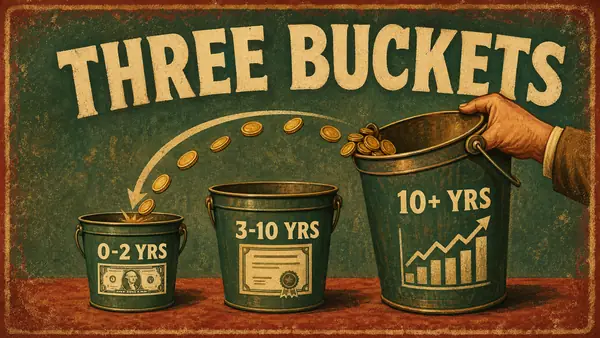
Retirement bucket strategy for the decade before retirement: split cash, bonds, and stocks to reduce sequence risk and make withdrawals calmer across accounts.
Press, partnerships, or a question about either product? Write to us. A person reads every message, and it is usually the founder.